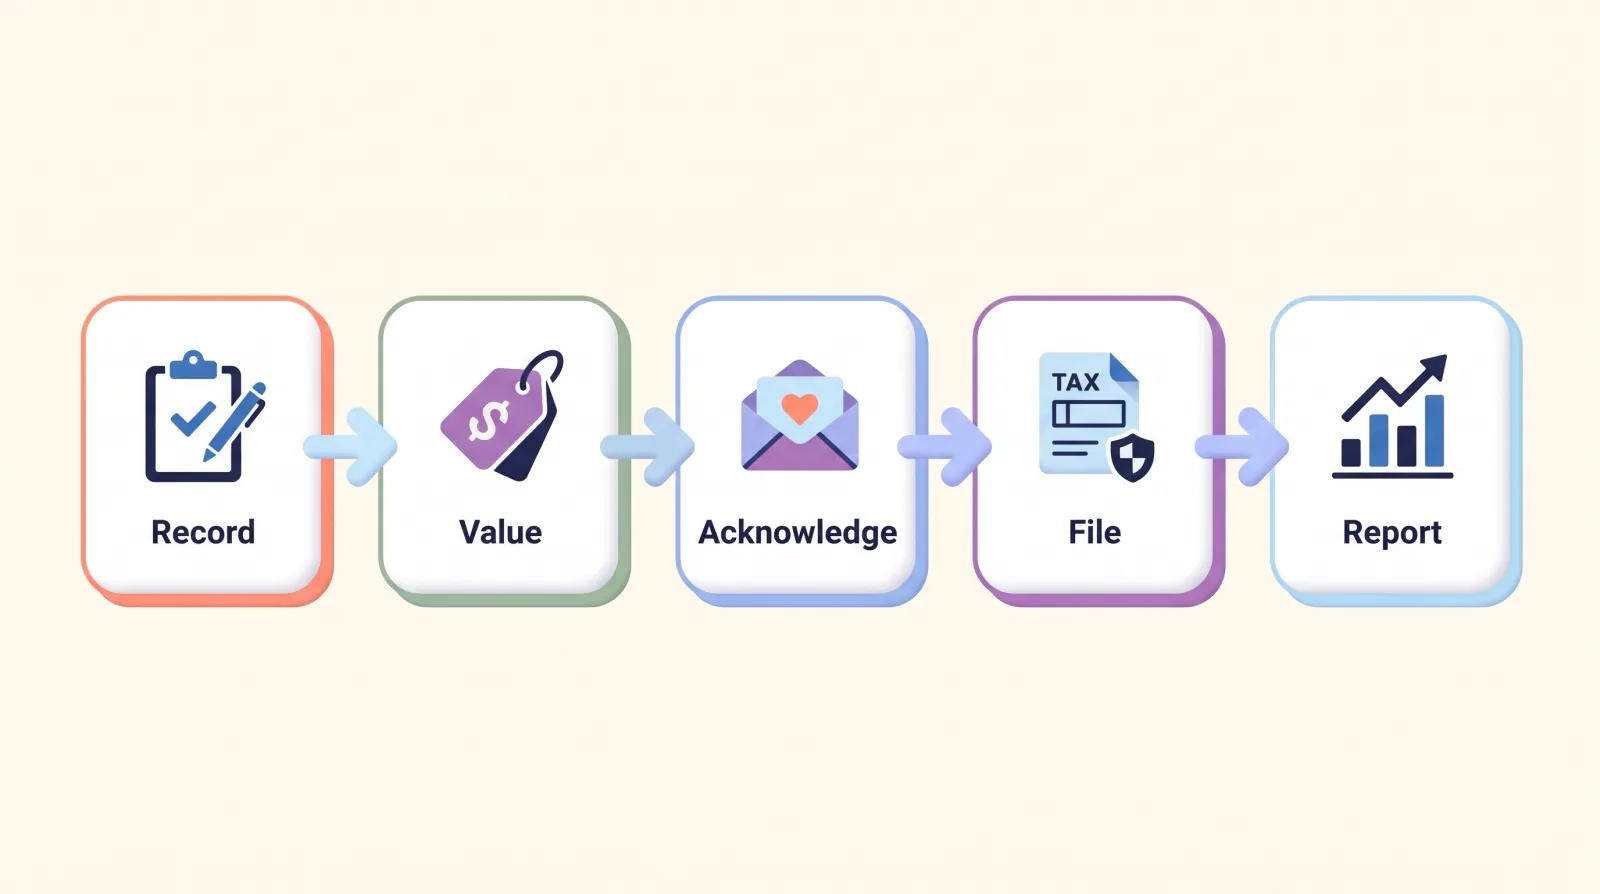
TL;DR: To track in-kind donations, record every non-cash gift within a few days of arrival, assign a documented fair value for your books, send a written acknowledgment that describes the gift without valuing it, and report gifts in kind as their own line in your financial statements.
A local printer donates 5,000 event programs. A law firm reviews your lease pro bono. A board member's company covers the venue for your gala. None of that money touched your bank account, and all of it belongs in your records.
This guide walks through how to track in-kind donations from intake to audit: what to record, how to value non-cash gifts, what the IRS expects in your acknowledgment, when Forms 8283 and 8282 apply, and how gifts in kind land in your financial statements. It's written for development teams that already handle a steady flow of donated goods and services and want a process finance, fundraising, and the auditor can all live with.
The short version: treat every in-kind gift like a cash gift with two extra jobs. Document a fair value for your own books, and write a receipt that deliberately leaves that value out.
What counts as an in-kind donation, and what doesn't?
An in-kind donation is a gift of goods, services, or property instead of cash. Accountants call these contributed nonfinancial assets, and the IRS calls them noncash contributions. Same thing, different paperwork.
The most common categories for growing nonprofits:
- Goods and supplies: food, clothing, equipment, furniture, technology, printed materials, and auction items
- Professional services: legal work, accounting, design, consulting, or medical care performed by someone with that credential
- Use of space or property: donated or discounted rent, venue space, storage, or vehicles you'd otherwise pay for
- Bills paid on your behalf: a donor who pays your printer, caterer, or utility company directly
- Real estate, securities, and other property: less frequent, higher value, and subject to extra filing rules covered below
Three things people assume are in-kind gifts but usually are not:
- General volunteer time. The volunteer can't deduct it. IRS Publication 526 is explicit that the value of time or services is never deductible, though out-of-pocket expenses can be.
- Most services. They only belong on your books in narrow cases, typically specialized skills you'd otherwise have had to pay for.
- Gifts earmarked for a specific person. A gift directed to an individual rather than your organization isn't a contribution to you at all.
When you're unsure whether something qualifies, record it anyway with a note. Reclassifying a documented gift is easy. Reconstructing an undocumented one during an audit is not.
Step 1: How do you record an in-kind donation when it arrives?
Recording is where most in-kind tracking falls apart, because the gift shows up at a loading dock, a gala, or a program site instead of a donation form. Build a habit that gets every non-cash gift into your donor database within a few days, in the same record structure you use for cash.
For each in-kind gift, capture:
- Donor (individual or company, plus the contact person if it's a business)
- Date received, not the date someone remembered to enter it
- Description specific enough that a stranger could picture it: quantity, condition, brand or model, and what it was for
- Gift type flagged as in-kind so it never blends into your cash totals
- Fund, campaign, or program it supports, and any donor restriction on how you use it
- How it arrived and who accepted it on your team
- Supporting documents: photos, packing slips, invoices, a donor's own statement of value, or an appraisal
If a company donates the goods but an employee arranged it, give the company the hard credit and the employee a soft credit so both relationships stay visible without double counting revenue. The same applies when a donor pays a vendor directly on your behalf.
This is easier when your donor database has a real in-kind gift type instead of a dollar field with a note. DonorDock's in-kind gifts feature lets you log the description, estimated fair market value, date, and donor on one record, and the gift shows on the donor's timeline next to their cash gifts and event attendance. If your current system can't do that, it's time to evaluate a nonprofit CRM that treats non-cash giving as real giving.
Step 2: How do you value in-kind donations?
Two different people value the same gift for two different purposes, and mixing them up causes most of the confusion.
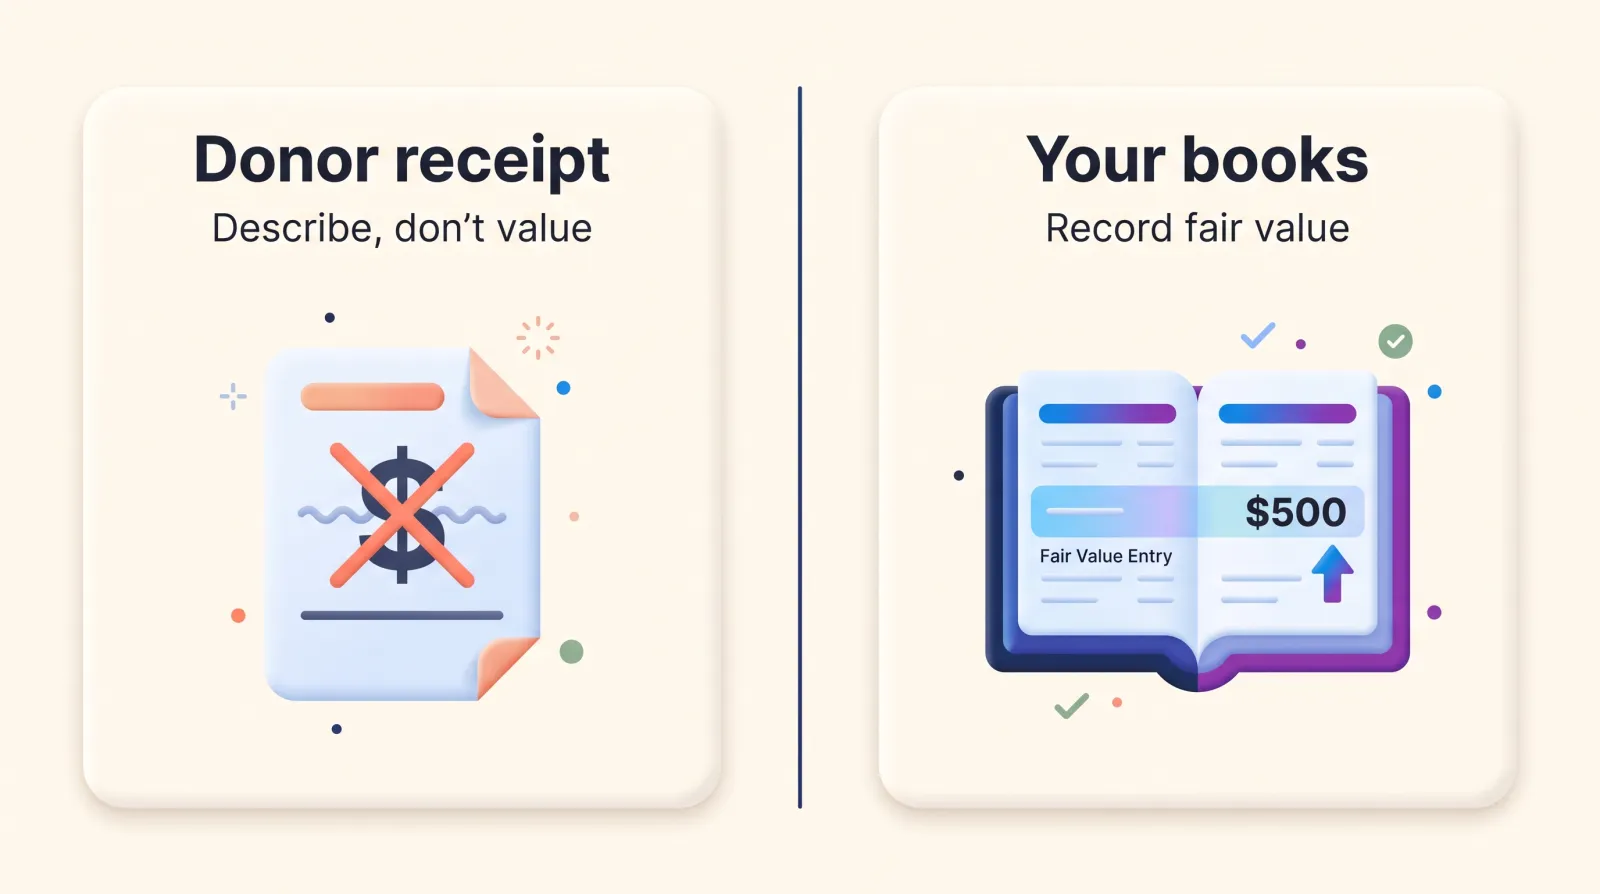
For the donor's tax deduction, the donor sets the value. The IRS is clear that a charity's written acknowledgment should describe non-cash property without stating its value. Your job is to describe the gift accurately. Their job, with their tax preparer, is to decide what it was worth.
For your own books, you set the value. Accounting standards require you to record contributed nonfinancial assets at fair value, meaning what you would pay for the same item or service in its principal market on the date received. That figure feeds your statement of activities, your Form 990, and your grant reports.
Practical ways to arrive at fair value
- New goods: the retail price a typical buyer would pay, or wholesale if you received a quantity a buyer would normally source in bulk
- Used goods: thrift or resale pricing for the same item in similar condition
- Professional services: the provider's standard billing rate or the local market rate, backed by an invoice marked as donated
- Space and facilities: the rent a comparable tenant would pay for the same space and term
- Donated media or advertising: the rate card, adjusted for any discount you would normally negotiate
Write down the method and the source for every valuation. Under FASB's ASU 2020-07, your financial statements must describe the valuation techniques and inputs you used for each category of gifts in kind, so a note like "retail price from vendor quote dated March 3" saves your finance team real time at year end.
What about volunteer hours?
Volunteer time rarely belongs in your revenue, but it belongs in your story. Independent Sector estimates the value of a volunteer hour at $36.14 for 2025. Use that number in impact statements, board dashboards, and grant narratives. Keep it out of your general ledger unless your auditor confirms the hours meet the specialized-skills test.
Step 3: What does the IRS require in an in-kind donation acknowledgment?
A donor can't claim a deduction for any single contribution of $250 or more without a contemporaneous written acknowledgment from your organization. That rule applies to non-cash gifts exactly as it does to checks. Per the IRS written acknowledgment requirements, your letter, email, or receipt needs to include:
- The name of your organization
- The date of the contribution
- A description of the non-cash property, without a dollar value
- A statement that no goods or services were provided in exchange, if that's true
- If you did provide something in return, a description and good-faith estimate of the value of those goods or services
- If applicable, a statement that the only benefit was an intangible religious benefit
Contemporaneous means the donor has the acknowledgment before they file their return or before its due date, whichever comes first. Don't wait for that deadline. Sending it within a week or two of receipt is the stewardship standard, and it is the moment the donor most wants to hear what their gift made possible.
One related rule catches teams off guard. If a donor gives more than $75 and receives something in return, such as a gala ticket, the quid pro quo disclosure rule requires you to tell them how much of their payment is deductible. Your good-faith estimate applies to what you gave them, never to what they gave you.
A receipt template that stays compliant
Use this structure and let your database fill in the fields. In DonorDock, acknowledgment letters pull the gift description, date, and the no-goods-or-services statement straight from the gift record.
Dear [donor first name], thank you for your generous in-kind contribution to [organization name] on [gift date]. You donated [gift description, quantity, and condition], which supports [program or purpose]. No goods or services were provided in exchange for this contribution. Because we describe but do not value non-cash gifts, please consult your tax advisor about the deductible amount. With gratitude, [signer name and title].
Notice what's missing: any dollar figure. If your current letters include one, remove it. A value on the receipt implies your organization is certifying the deduction, and that's the donor's responsibility, not yours.
Step 4: When do Form 8283 and Form 8282 come into play?
Larger non-cash gifts trigger donor filing requirements, and two of them put paperwork on your desk.
Per IRS Tax Topic 506, a donor who claims more than $500 in total noncash deductions for the year must file Form 8283 with their return. If any single item or group of similar items is worth more than $5,000, the donor also needs a qualified appraisal, with publicly traded securities as the main exception.
This is where your signature enters the picture. For gifts over $5,000, the donor will ask you to sign Section B, Part V of Form 8283 as the donee. Your signature confirms you received the property on the stated date and understand the reporting rules. It doesn't mean you agree with the appraised value, and your organization cannot serve as the appraiser.
Form 8282 is the follow-through. If you sell, exchange, or otherwise dispose of that property within three years, you must file Form 8282 with the IRS within 125 days and send the donor a copy. The main exceptions are property worth $500 or less when you signed the 8283 and property you consumed or distributed in carrying out your mission.
The practical takeaway: keep a disposition log for every gift where you signed a Form 8283, and store the signed form on the gift record so the 8282 deadline never depends on someone's memory.
Step 5: How do in-kind donations show up in your financial statements?
For fiscal years beginning after June 15, 2021, nonprofits follow FASB Accounting Standards Update 2020-07 for gifts in kind. The standard did not change how you value non-cash gifts. It changed how visibly you have to present them. The update requires you to:
- Present contributed nonfinancial assets as a separate line item in the statement of activities, apart from cash and other financial contributions
- Disaggregate gifts in kind by category, such as food, professional services, facilities, or supplies
- Disclose, for each category, whether the assets were used in programs or monetized, and your policy on selling rather than using them
- Disclose any donor-imposed restrictions on the gifts
- Describe the valuation techniques and inputs you used to arrive at fair value, and, where a donor restriction bars you from selling the assets, the principal market you used
Every one of those disclosures gets easier when you did Steps 1 and 2 well. If each gift record carries a category, a use, a restriction flag, and a valuation note, your auditor can build the footnote from a report instead of an email thread.
Keeping your CRM and QuickBooks in agreement
Most development teams record in-kind gifts in the donor database and let finance make the accounting entry in QuickBooks. That split is healthy, as long as the two systems agree at month end. A workable routine:
- Record the gift in your donor database with its fair value and category, flagged as in-kind
- Exclude in-kind gifts from the automatic cash sync so they never post as sales receipts or deposits
- Send finance a monthly in-kind report grouped by category, with valuation notes attached
- Finance books each category as contribution revenue and a matching expense or asset, per your accountant's guidance
- Reconcile the report total against the in-kind revenue line before closing the month
With DonorDock's QuickBooks integration, received gifts sync to QuickBooks Online every hour, and reusable gift filters let you hold in-kind gifts back from that sync so finance can enter them deliberately. The donor database stays the source of truth for who gave what, and the general ledger stays clean.
How should you report in-kind donations to your board and donors?
Once the compliance work is handled, in-kind data becomes one of the most persuasive numbers you have. For the board, present in-kind giving by category alongside cash, with a note on what those gifts replaced in the budget. A donated venue is an expense you did not incur. For donors and corporate partners, mention the gift in annual giving statements and impact reports using the same language as the receipt: describe it, connect it to outcomes, skip the dollar figure.
Treat non-cash supporters as donors in every other sense too. They belong in your stewardship sequence, your retention math, and your event invitations. A company that donated printing this year is a sponsorship prospect next year. If your database is missing the fields to make that visible, start with the 10 donor data points every nonprofit should collect and a data hygiene routine that keeps in-kind records as clean as cash ones.
One caution: accepting every offered gift is not stewarding in-kind giving well. Items you cannot use consume storage, staff time, and disposal budget, and saying yes to them is a quiet form of mission drift. A board-approved gift acceptance policy gives your team permission to decline gracefully.
What does a complete in-kind tracking checklist look like?
If a gift record can answer every question below, you're ready for the acknowledgment, the audit, and the board meeting.
- Is the gift flagged as in-kind, with donor, date, and a specific description?
- Is the fair value recorded, with the method and source behind it?
- Is the gift assigned to a category, a fund or program, and any donor restriction?
- Was a written acknowledgment sent that describes the gift and omits the value?
- If the donor received anything in return, was the deductible portion disclosed?
- For gifts over $5,000, is the signed Form 8283 stored on the record with a disposition log?
- Is the gift excluded from the cash sync and included in the monthly report to finance?
- Does the donor's timeline show the gift next to their cash giving?
Non-cash gifts ask a little more of your process than checks do. In return, they tell a fuller story about who stands behind your mission. Give them the same home as every other gift, and tracking stops being a year-end scramble and becomes part of how you steward people who give in every way they can.
To see how in-kind gifts, acknowledgment letters, and QuickBooks sync fit together in one platform, schedule a DonorDock demo and bring a real gift record to walk through.