To track restricted gifts, record each one against the fund it was given for, in both your donor database and your books, and release the restriction once it's met. Since FASB's ASU 2016-14, every fund you track rolls up into one of two net asset classes: with or without donor restrictions.
Nonprofit fund accounting is the practice of tracking money by purpose. Fund accounting for nonprofits records each gift against the fund it was given for, so you can show how much came in, how much was spent, and how much remains for that purpose. It's how you prove to donors, grantors, and auditors that restricted dollars went where you promised.
Here's what that looks like day to day. A donor who gave $25,000 to your scholarship fund last spring asks a fair question: how much has been used, and how many students did it reach? Your board treasurer wants to know how much of the cash on the balance sheet is actually free to spend. Your auditor wants a schedule of every restricted gift and the date each restriction was met.
All three are fund accounting questions. If answering them takes a week of spreadsheet work, the problem usually isn't your people. It's how gifts are being tracked.
What is nonprofit fund accounting?
A fund is any pool of money you need to track separately because someone, usually a donor, a grantor, or your board, has said what it's for. Your general operating fund is one. A scholarship fund, a capital campaign, a federal grant, and an endowment are others.
Here's a quick test. Ask yourself: do I need to know how much money is set aside for, and spent on, this purpose? If the answer is yes, it's probably a fund.
Nonprofits also use a slightly different accounting equation. A business has owners, so its books end in equity. A nonprofit has no owners, so its books end in net assets: assets minus liabilities equals net assets. Fund accounting splits that number by purpose, so your board sees not only how much you have but how much of it is free to use.
How is nonprofit fund accounting different from for-profit accounting?
- What's left over. A business reports owners' equity. A nonprofit reports net assets, because nobody owns the surplus.
- What success looks like. A business measures profit. A nonprofit measures whether it delivered its mission while honoring every restriction attached to the money.
- What the statements are called. Nonprofits produce a statement of financial position, a statement of activities, a statement of cash flows, and an analysis of expenses by function and nature.
- How often money comes with strings. Restrictions are rare in business and routine in nonprofits, which is why gifts are tracked by fund.
One note on terms. This guide covers private nonprofits that follow FASB standards. Government entities follow GASB rules, where "fund accounting" means a fully separate, self-balancing set of books for each fund. Most growing nonprofits don't need that. They need restrictions tracked accurately, by fund, in a donor database and an accounting system that agree.
Why does fund accounting matter to your development team?
Because a restricted gift is a promise, and fund accounting is how you keep it. Honoring a donor's designation is the most basic form of stewardship, and being able to show exactly how a gift was used is what earns the next one.
- Donor trust. When a donor designates a gift, they expect it to be used that way. Our guide to honoring donor intent covers what happens when organizations get this wrong.
- Grant compliance. Under the Uniform Guidance, federal award recipients must keep records that sufficiently identify the amount, source, and expenditure of federal funds for each award. Foundations ask for budget-versus-actual reports by grant. Both are fund reports.
- Real liquidity. Restricted cash can't pay for just any expense. In Nonprofit Finance Fund's 2025 survey, 52 percent of nonprofits surveyed had three months or less of cash on hand. When cash is that tight, knowing which dollars are truly available isn't optional.
- Audit and Form 990. Form 990, Part X reports net assets without donor restrictions and net assets with donor restrictions on separate lines. Auditors test whether each restriction was honored and released properly.
Major donors and grant funders read those same numbers closely. Our guide to what funders look for in nonprofit financial statements walks through exactly what they check.
What are the two net asset classes under ASU 2016-14?
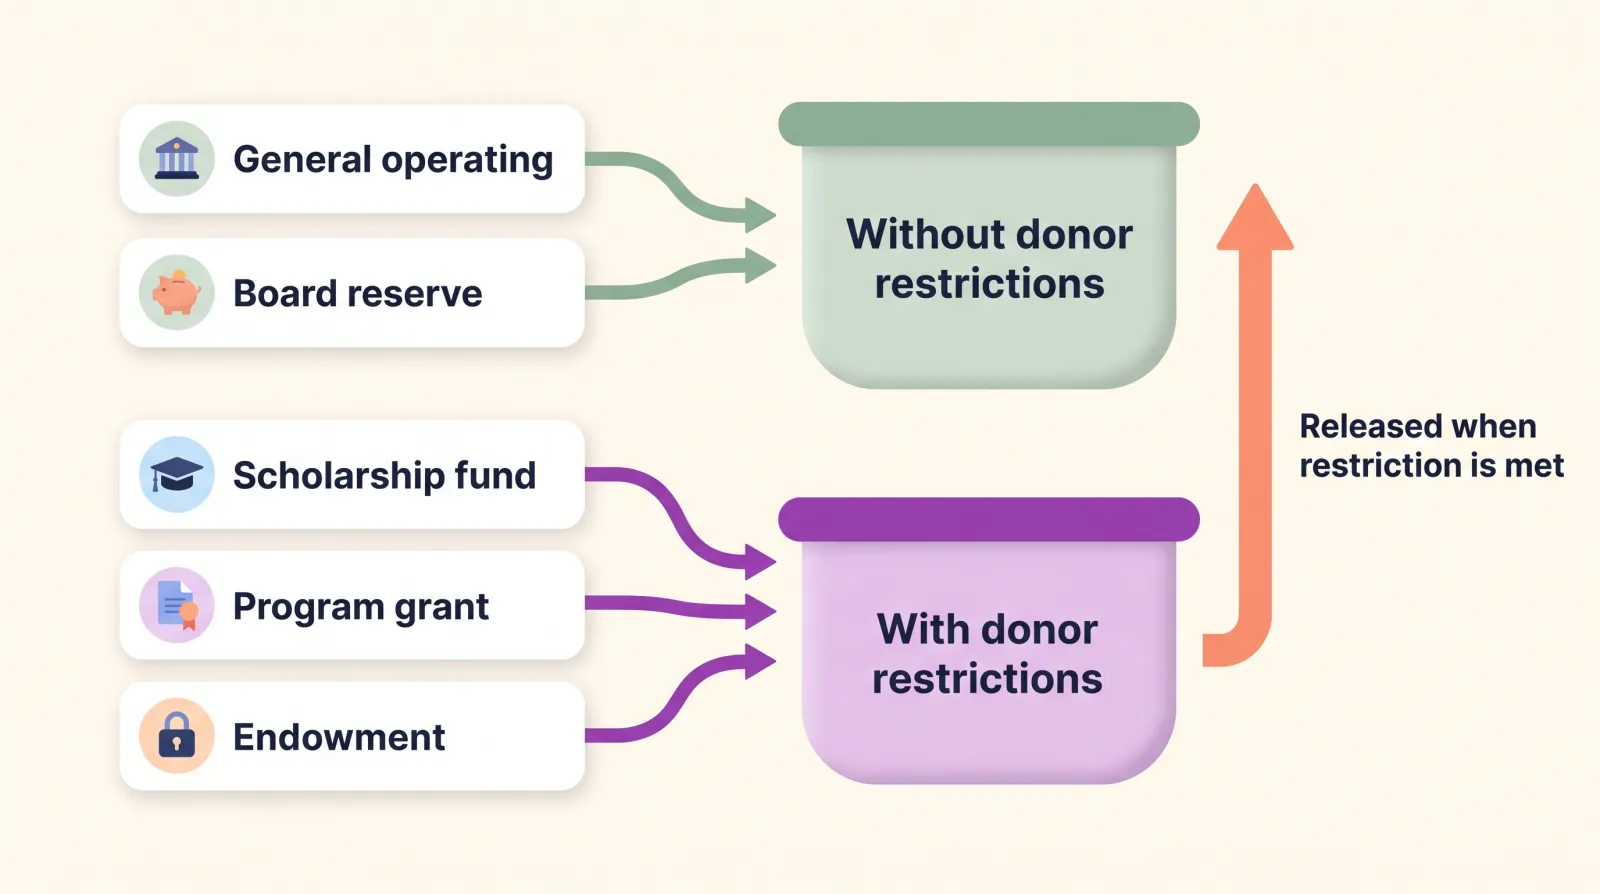
If your reports still say "temporarily restricted" or "permanently restricted," you're not alone, but FASB retired those labels years ago. ASU 2016-14, issued in August 2016 and effective for fiscal years beginning after December 15, 2017, collapsed three net asset classes into two:
- Net assets without donor restrictions. Money you can use for any purpose within your mission, including amounts your board has chosen to set aside. Examples: general operating gifts, unrestricted bequests, board-designated reserves, and quasi-endowments.
- Net assets with donor restrictions. Money a donor or grantor has limited by purpose or by time, including gifts meant to be held in perpetuity. Examples: a scholarship gift, a pledge for next year's programs, a capital campaign gift, and a donor-restricted endowment.
In practice, "unrestricted" became "without donor restrictions," and the old temporarily and permanently restricted classes were combined into "with donor restrictions." Your notes to the financial statements now explain the nature and amount of those restrictions.
Board-designated funds stay unrestricted
If your board sets aside an operating reserve or creates a quasi-endowment, that money is still without donor restrictions, because the board can reverse its own decision. ASU 2016-14 requires you to disclose board designations, but they don't move money into the restricted class.
What else did ASU 2016-14 change?
- A liquidity disclosure. You explain, in words and numbers, how much of your financial assets are available to meet general expenses within one year.
- Expenses by function and nature, in one place. Program, management and general, and fundraising costs are shown alongside salaries, rent, and other natural categories.
- Underwater endowments. When a donor-restricted endowment falls below its original gift value, the shortfall is reported within net assets with donor restrictions.
All three changes depend on tracking funds during the year, not just at year-end. The liquidity disclosure in particular is hard to write if restricted and unrestricted cash weren't kept apart all along.
How do you account for donations to nonprofit organizations?
Every gift follows the same path: classify it, record it in the right fund, and release the restriction when it's met.
- Check for a donor restriction. Look at the gift agreement, pledge form, reply device, or grant award letter. Restrictions can be stated outright ("for scholarships") or implied by the circumstances, such as a gift made in response to an appeal for a specific project. When in doubt, ask the donor and write down the answer.
- Decide whether it's conditional. Under ASU 2018-08, a contribution is conditional only when the agreement includes both a barrier you must overcome and a right of return or release if you don't. Unconditional gifts and pledges are recorded when received or promised. Conditional ones wait until you meet the condition. Matching grants are a common example.
- Record it at fair value. Cash is recorded at face value. An unconditional pledge becomes a contribution receivable. Donated stock is recorded at its fair value on the date you receive it. Gifts in kind appear on their own line in the statement of activities under ASU 2020-07, and our guide to tracking in-kind donations covers the details.
- Code the same fund in both systems. The fund on the gift in your donor database should match the class or account your finance team uses in the books.
- Release the restriction when it's met. When you spend restricted money on its purpose, or a time restriction passes, reclassify that amount from with donor restrictions to without donor restrictions. On the statement of activities it appears as "net assets released from restrictions."
Fund accounting in action
Picture a summer camp that serves kids from under-resourced neighborhoods. It runs on general operating support, a scholarship fund, and a foundation grant for a summer reading program.
In March, a donor gives $10,000 to the scholarship fund. In June, the camp spends $2,500 to send five campers. Here's how that flows:
- March gift: $10,000 recorded in the scholarship fund, with donor restrictions.
- June spending: $2,500 released from restriction and recorded as a program expense.
- June 30 balance: $7,500 still with donor restrictions, available only for scholarships.
The reading program grant works the same way. When the camp spends $5,000 on books and counselor hours for the program, that amount is released from the grant fund. If the grant had required the camp to raise matching funds first, with the right to take the money back otherwise, it would be conditional and wouldn't count as revenue until the match was met.
At any moment, the camp can tell its scholarship donor exactly what the gift did and what's left to spend. That's the whole point.
How does grant accounting fit into fund accounting?
Treat every grant as its own fund. That one habit answers most grant reporting questions before a program officer asks them.
- Budget each grant. Set up the approved grant budget so you can report budget versus actual by line item at any point in the grant period.
- Know whether it's a contribution or an exchange. If the funder receives something of roughly equal value in return, it's an exchange transaction and follows revenue recognition rules instead. A benefit to the general public doesn't count as value to the funder, so most grants, including many government grants, are contributions.
- Track indirect costs. Federal recipients without a negotiated rate can charge a de minimis indirect cost rate of up to 15 percent of modified total direct costs. Our grant readiness checklist shows how to compare that rate to your real overhead before you apply.
- Watch the single audit threshold. An organization that spends $1,000,000 or more in federal awards in a fiscal year beginning on or after October 1, 2024 must have a single audit. Clean grant funds make that audit faster and less costly.
How do you set up fund accounting at a growing nonprofit?
You don't need new books to do this well. You need a short list of funds, a shared map between your systems, and a monthly rhythm.
- List the funds you actually need. Use the test above. You probably need fewer funds than you think. Ten well-defined funds beat forty that nobody can explain.
- Keep funds separate from campaigns and appeals. A fund says what the money is for. A campaign or appeal says how you raised it. Your year-end appeal isn't a fund. The general operating fund it raises money for is.
- Map each fund to your chart of accounts. Build a one-page sheet listing each fund in your donor database, the matching class or account in your books, and its restriction type. Have development and finance both sign off.
- Document restrictions at the moment of the gift. Attach the gift agreement or award letter to the gift record so a restriction never depends on someone's memory.
- Code gifts at entry. Assign the fund when the gift is entered, not at month-end. Let donors pick a designation on your giving page so the fund arrives with the gift.
- Release and reconcile every month. Review spending against restricted funds, record the releases, and reconcile your donor database with QuickBooks before you close the month.
- Report by fund. Give your board a quarterly fund balance summary, and give restricted donors a short update on what their gift accomplished.
What fund accounting mistakes should you avoid?
- Coding a restricted gift as general support. It's the most common error and the most consequential, because the money looks spendable when it isn't.
- Never releasing restrictions. If you spend restricted money but don't record the release, restricted balances grow on paper and your operating results look worse than they are.
- Creating a fund for every appeal. Funds multiply, balances fragment, and fund reports stop meaning anything.
- Splitting costs without a method. If an expense truly serves two funds, allocate it on a documented basis such as staff time or square footage. Otherwise, pick one fund.
- Using retired labels. Old labels like "temporarily restricted" on a current board report invite questions from your auditor. Updating them is a quick fix.
- Naming funds differently in each system. "Scholarships" in one place and "Camp Aid" in the other guarantees a reconciliation problem every month.
What software do nonprofits use for fund accounting?
Fund accounting lives in two systems that have to agree. Your accounting system holds the official books. Your donor database, or nonprofit CRM, holds the gift, the donor, the designation, and the paperwork behind each restriction.
Many growing nonprofits keep their books in QuickBooks Online and track funds with class tracking, which Intuit offers on its Plus and Advanced plans. Organizations with many grants or complex cost allocations often move to dedicated nonprofit accounting software. Either way, the donor side matters just as much, because that's where restrictions are captured in the first place.
On the donor side, look for:
- Fund designations donors can choose on your online giving form
- A fund on every gift record, with the restriction documentation attached
- Gift reports you can filter by fund, campaign, and date range
- Receipts that confirm the fund the donor chose
- A mapping between your funds and your accounting classes or accounts
- A gift-level sync with a reference number on both sides
In DonorDock, donors can designate gifts to specific funds on your Giving Pages, and you can merge the fund into their receipt so they know the gift arrived where they intended. The QuickBooks Online integration syncs gifts as sales receipts and lets you map each fund to a QuickBooks class, so your fund list and chart of accounts stay aligned. Gift reports filter by fund, campaign, date range, and gift type, and every synced gift carries its DonorDock gift number for easy cross-checking. For more on how the two systems divide the work, see how DonorDock and QuickBooks work together.
If finance and development are choosing tools together, our guide to getting finance and fundraising aligned on your CRM helps both teams score vendors on the same criteria.
Start with your fund list
Fund accounting doesn't start with software or a new chart of accounts. Start by listing your funds, retiring any that are really campaigns, and updating reports that still use pre-2018 labels. Then reconcile one month and see how closely your two systems agree.
When the year winds down, our year-end close tips pick up where your monthly routine leaves off.
Want to see how a donor's fund designation flows from your giving page to a QuickBooks class? Book a demo and we'll walk you through it.